
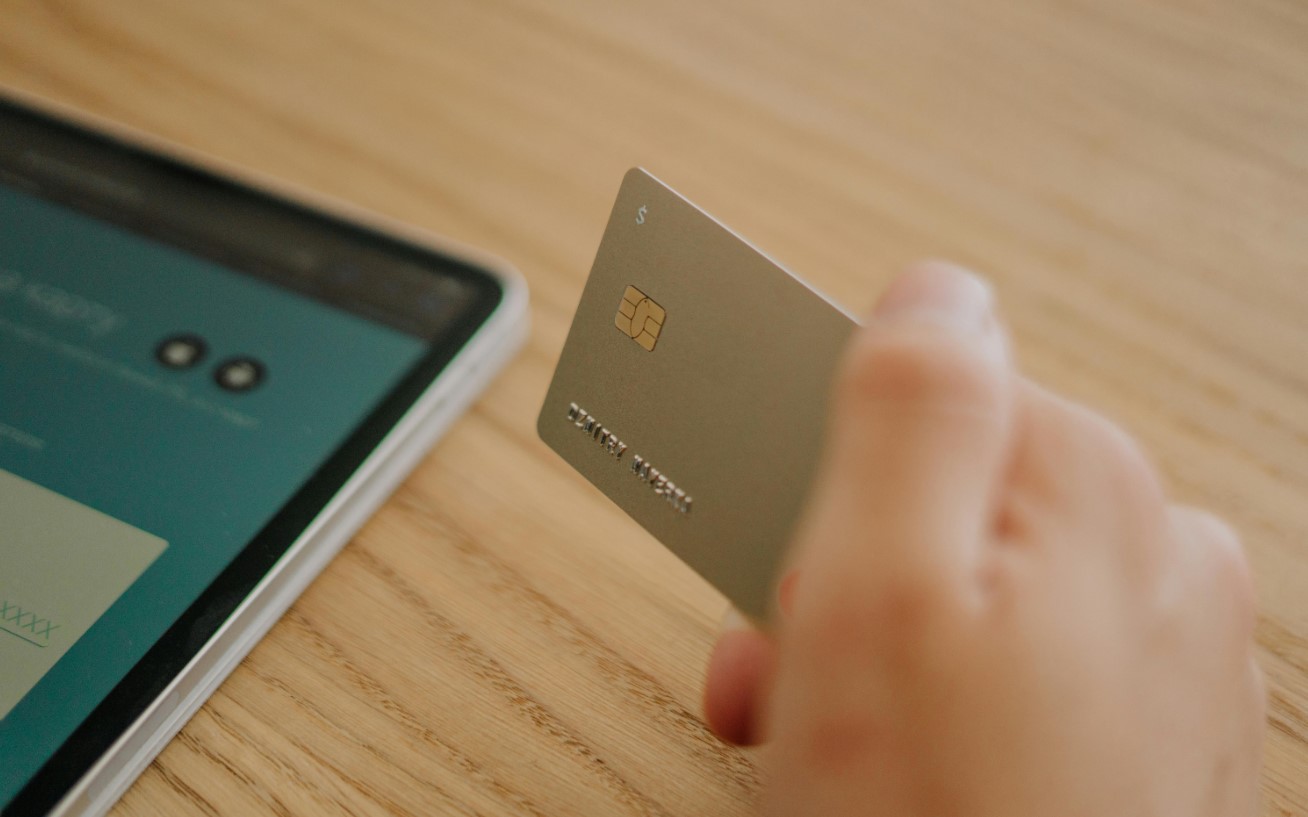
Cyprus among beneficiaries of drive to make European payments cheaper
The European Central Bank (ECB) has urged greater public awareness of the Single Euro Payments Area (SEPA), warning that households across south-eastern Europe continue to rely on costly money transfer services despite the availability of cheaper cross-border payment options.
In a recent blog post, the ECB said that SEPA now connects 41 European countries, allowing euro transfers between participating countries to be made as easily and inexpensively as domestic payments, yet many consumers remain unaware of the system and its benefits.
The findings have particular relevance for countries such as Cyprus, where digital payments and instant transfers have expanded rapidly, but where the wider transition towards integrated European payment services continues to evolve.
The ECB’s analysis draws on the OeNB Euro Survey, examining six south-eastern European countries and highlighting the importance of remittances, the costs of transferring money and the relatively limited public understanding of European payment integration.
Every year, migrant workers across the euro area send billions of euro to support relatives in other EU countries and neighbouring states aspiring to join the bloc.
Bulgaria, the euro area’s newest member, receives almost €3 billion in remittances annually, while inflows to Albania exceed €2.5 billion and represent around 8.4 per cent of its gross domestic product, compared with 2.1 per cent in Bulgaria.
At household level, around one in five people in Albania, or 21 per cent, reported receiving remittances, compared with 17 per cent in Bosnia and Herzegovina, 10 per cent in North Macedonia, nine per cent in Serbia, eight per cent in Bulgaria and four per cent in Romania.
Despite the importance of these transfers, traditional banking channels remain far from dominant.
Across the six countries surveyed, approximately one-third of remittance recipients receive money in cash through relatives or friends, while another third use physical money transfer operators.
The differences between countries are considerable, with bank-based transfers more commonly used in Bulgaria, while more than half of recipients in Albania rely on money transfer operators.
These alternatives can be expensive, with cash-to-cash transfers typically attracting fees of between six and 12 per cent, while digital transfers through non-bank providers can cost between 1.5 and 4.5 per cent.
Depending on the countries involved, provider and payment channel, fees for the same transfer can differ by more than 10 percentage points.
The ECB estimated that a five per cent transfer fee would amount to approximately €140 million on Bulgaria’s annual remittance inflows and €130 million on those received by Albania.
By contrast, SEPA transfers are designed to make cross-border euro payments as straightforward and inexpensive as domestic transactions, particularly when recipients hold euro-denominated accounts and can avoid currency conversion charges.
Before SEPA was introduced, cross-border euro transfers were often slower, involved different national standards and attracted considerably higher fees.
Its geographical scope now includes all euro area countries, EU member states outside the euro area and an increasing number of candidate countries.
Bulgaria and Romania have been included for more than 15 years, while Albania and North Macedonia joined in 2024 and Serbia in 2025.
Bosnia and Herzegovina formally applied for membership in August 2026.
However, the ECB cautioned that inclusion in SEPA’s geographical scope does not automatically mean a fully operational payment system is immediately available.
Despite its expansion, public awareness remains surprisingly limited.
Fewer than 40 per cent of consumers surveyed had heard of SEPA, regardless of how long their country had been included in its geographical scope.
Awareness was higher among people with greater incomes, education and financial literacy.
Consumers with tertiary education were around 17 percentage points more likely to have heard of SEPA than those with only primary education.
The ECB also pointed out that awareness of crypto-assets was considerably higher, despite fewer than one in ten consumers in the surveyed countries owning them, with the highest ownership rate reaching just six per cent.
It acknowledged that greater awareness does not necessarily translate into different financial decisions, citing research suggesting that providing information about deposit insurance guarantees can improve awareness without significantly changing consumer behaviour.
Nevertheless, it argued that even relatively small changes in payment choices could produce meaningful savings for households.
For migrant workers sending money home, replacing expensive cash-based services with SEPA transfers could deliver immediate financial benefits, alongside greater convenience, speed, reliability and security.
Cyprus has made considerable progress in its own transition towards digital payments.
A Central Bank of Cyprus (CBC) report published in July 2026 found that non-cash payment transactions increased by eight per cent year on year to 174 million in the second half of 2025, while their total value rose by nine per cent to €148 billion.
Card payments accounted for 75 per cent of all non-cash transactions, giving Cyprus the highest proportion in the euro area, compared with an average of 57 per cent across the bloc.
The country has also made significant progress in instant payments.
Following the implementation of the EU Instant Payments Regulation, the proportion of instant transfers among all SEPA credit transfers in Cyprus increased from less than one per cent to almost 32 per cent by volume.
By value, their share climbed to approximately nine per cent, while the average instant payment amounted to €1,500, compared with €5,500 for traditional SEPA credit transfers.
EU rules requiring banks to process instant payments around the clock, with funds reaching recipients within ten seconds, became mandatory for sending payments on October 9, 2025.
The framework also introduced stronger safeguards, including verification of the beneficiary’s name against the account’s international bank account number (IBAN).
Cyprus is meanwhile preparing another development in domestic payments, with a proposed interbank service expected to allow customers to transfer money using only the recipient’s mobile phone number.
The service, which was being considered for introduction in the first quarter of 2027, would use mobile numbers as proxies linked to bank accounts, eliminating the need for customers to exchange IBAN details for eligible transfers.
The ECB’s latest findings underline that the next challenge is ensuring consumers understand and make full use of the payment infrastructure already available to them, rather than simply expanding the technology.
For Cyprus, which has advanced considerably in card payments and instant transfers, the wider European effort to make cross-border payments cheaper and more accessible could offer further benefits to households, businesses and workers with financial ties across national borders.
Click here to change your cookie preferences