
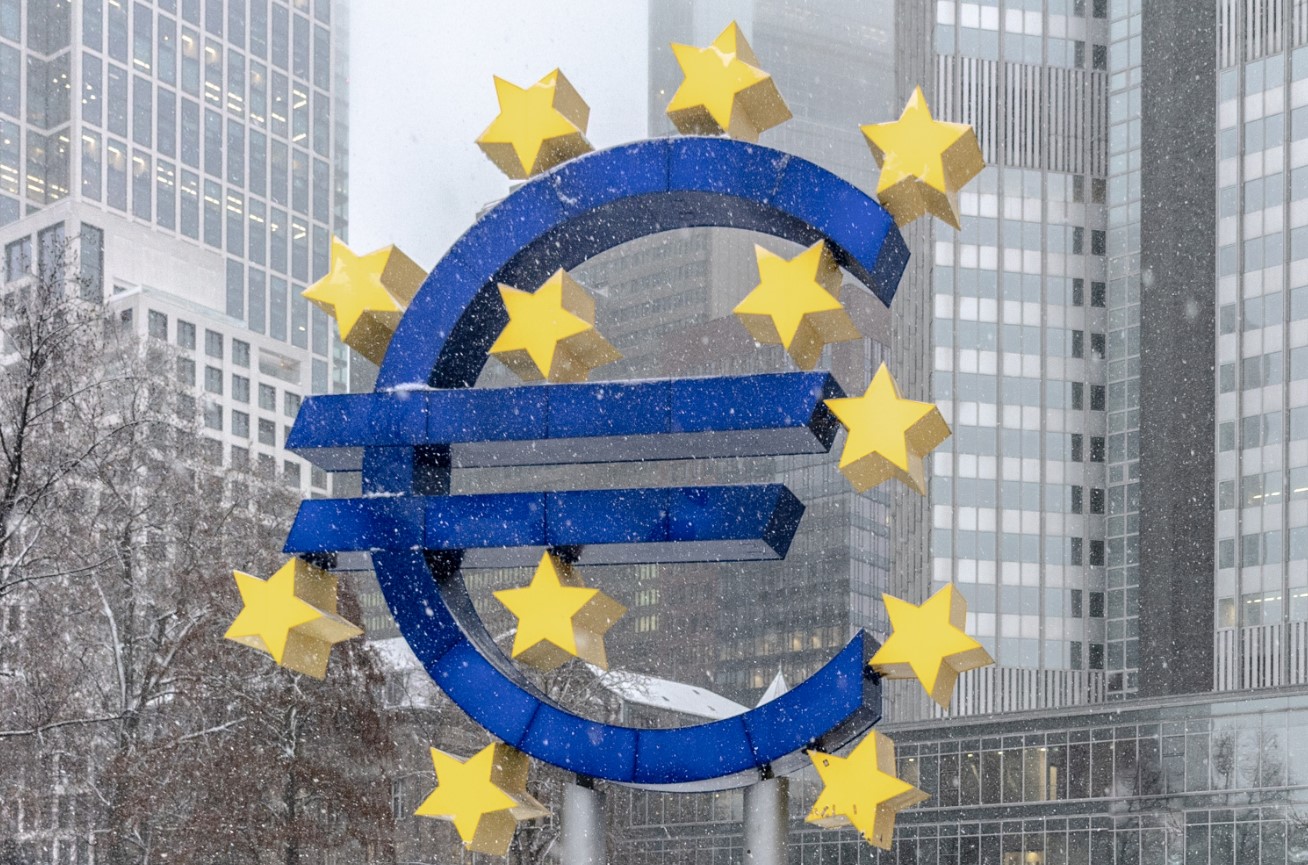
Strong capital buffers protect EU banks as geopolitical tensions persist
The European Banking Authority (EBA) recently released its risk dashboard for the second quarter of 2026, confirming that banks across the EU and EEA continue to operate from a position of strength despite an uncertain macroeconomic backdrop.
The report summarises the main risks and vulnerabilities of the regional banking sector using supervisory reporting data.
According to the findings, lenders display robust capital and liquidity buffers, sustained lending growth, sound asset quality, and high profitability.
However, the watchdog warned that unabating geopolitical tensions, buoyant financial markets, and challenging macroeconomic conditions require continuous monitoring.
The sector’s Common Equity Tier 1 ratio stood at 16.1 per cent, representing a slight decrease from the previous quarter due to an increase in risk-weighted assets.
Despite the small drop, banks maintain substantial capacity to absorb financial shocks, backed by approximately 430 basis points of headroom above regulatory requirements.
Liquidity positions remained firmly above minimum requirements, with a Liquidity Coverage Ratio of 158.5 per cent and a Net Stable Funding Ratio of 125.7 per cent.
High-quality liquid assets showed a continued expansion in sovereign bonds, which grew by 8.7 per cent during the first half of 2026 alongside a reduction in cash balances.
Lending to households increased by 5.2 per cent year-on-year, while loans to non-financial corporations expanded by 6.3 per cent over the same period.
Both categories recorded a quarterly increase of 1.7 per cent, though credit expansion remained uneven across different member states.
Asset quality remained remarkably sound across the region, with the non-performing loan ratio standing at 1.8 per cent.
The share of Stage 2 loans declined further to 8.9 per cent, even as conditions varied across specific sectors and countries.
Direct exposures to the technology sector accounted for 4 per cent of corporate lending, representing roughly 1.9 per cent of total client lending, with no signs of deteriorating credit quality.
Profitability showed further improvement across the industry, with the return on equity reaching 11.3 per cent compared with 10.7 per cent recorded a year earlier.
This performance was primarily driven by higher net interest income, supported by robust loan growth and widening net interest margins, which rose to 1.63 per cent.
Net fee and commission income also contributed to overall profitability, albeit to a lesser extent than net interest income.
Lenders kept operating costs broadly stable, enabling the cost-to-income ratio to fall from 52.5 per cent to 51.5 per cent on an annual basis.
Funding conditions remained highly favourable for banks, despite brief episodes of elevated market volatility.
Total deposits increased by 1.6 per cent, largely propelled by a 2.3 per cent rise in household deposits.
Nevertheless, the regulator emphasised that the external environment remains fraught with uncertainty.
Ongoing geopolitical tensions threaten to disrupt broader macroeconomic conditions, while expected interest rate increases could push up operating expenses and credit risk costs alongside bank profitability.
Additionally, asset valuations are widely viewed as elevated, particularly given the growing scale and concentration of funding directed toward artificial intelligence.
Click here to change your cookie preferences