
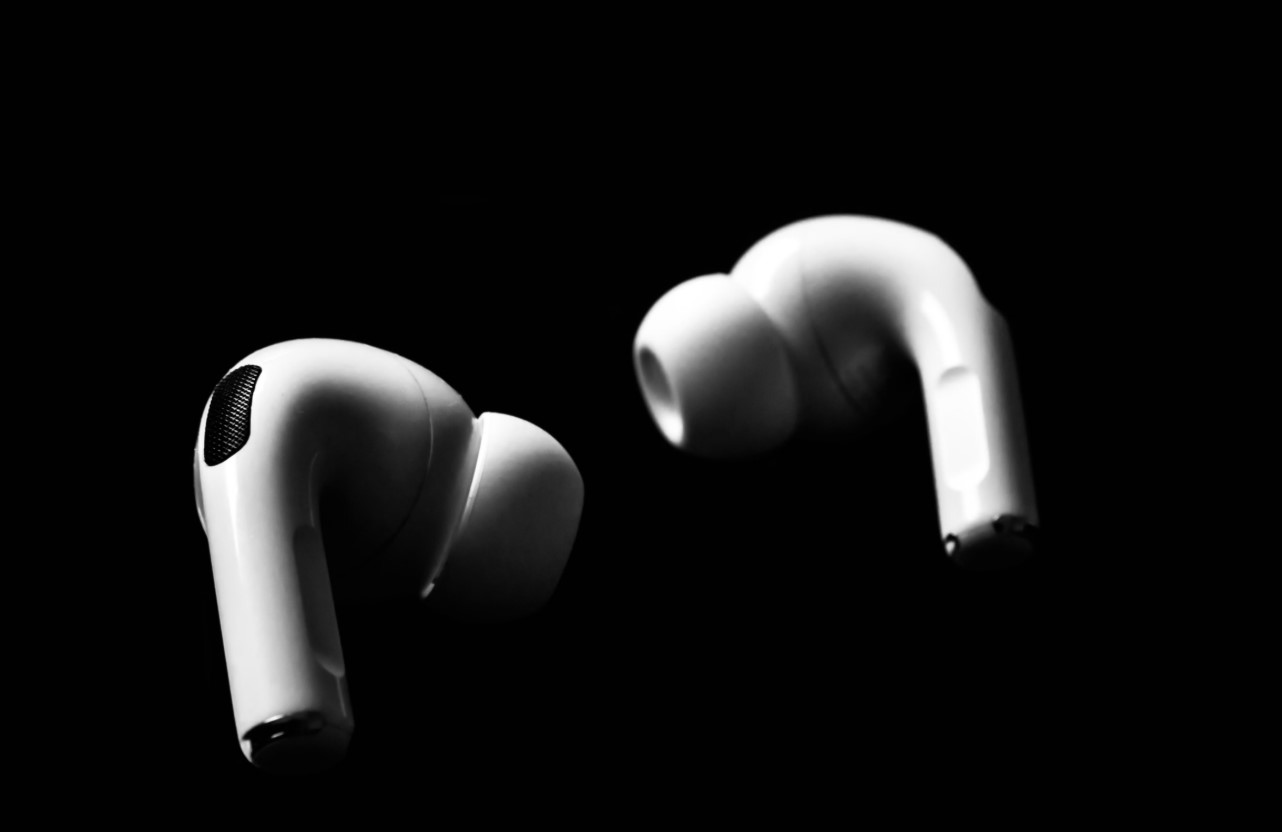
Global true wireless stereo shipments fell 0.7 per cent year-on-year to 82.1 million units in the second quarter of 2026, marking the first annual drop for the sector since mid-2023, technology research firm Omdia.
Mainland China, the world’s largest market, led the downturn with a 9.5 per cent fall as economic stimulus effects faded, whilst shipments also dropped in the United States and India.
The broader market stagnation masked a growing divergence between conventional in-ear models, which dropped two per cent, and open wireless stereo devices, which grew 12 per cent to 11.1 million units.
This expansion lifted open wireless stereo to 13.5 per cent of total shipments.
“The OWS category has a relatively low entry barrier, while product quality remains critical to differentiation, creating opportunities for a broad range of vendors,” Omdia Research Analyst Claire Qin stated.
“OWS is rapidly becoming an important area for new feature development, particularly around longer listening experiences and AI-enabled functionality across various usage scenarios,” she added.
Clip-on designs dominated open audio, representing 61 per cent of shipments due to fashion appeal, whilst ear-hook styles accounted for 39 per cent.
Massive growth occurred in both entry-level devices under 50 dollars, which rose 323 per cent, and the 100 to 199 dollar segment, which surged 253 per cent.
“The premium clip-on segment remains highly competitive, with sound quality a key area for differentiation,” Qin said.
“Vendors that address these challenges have greater scope to support premium pricing among consumers looking for a combination of functionality and style,” Qin added.
Fierce industry rivalry is concurrently driving rapid integration of artificial intelligence features, including neural processing units and large language model software.
“AI-driven features are becoming an important area of differentiation in premium audio, ranging from intelligent earbuds with integrated neural processing units to companion applications powered by large language models,” Omdia Research Director Jason Low explained.
“Users will continue to prioritise comfort, audio quality, call quality, and active noise cancellation performance,” he added.
“At the same time, AI features have the potential to support further adoption as consumers increasingly look for functionality that helps them complete tasks and improves the overall user experience,” Low continued.
Omdia projects annual open wireless shipments will climb from 43.9 million units in 2026 to 90.5 million units by 2030, capturing nearly a fifth of total industry volume.
“Successful vendors will need to tailor products to clearly defined use cases, such as fitness, commuting, and office productivity, while adding smarter features through seamless ecosystem integration,” Low concluded.
Click here to change your cookie preferences