
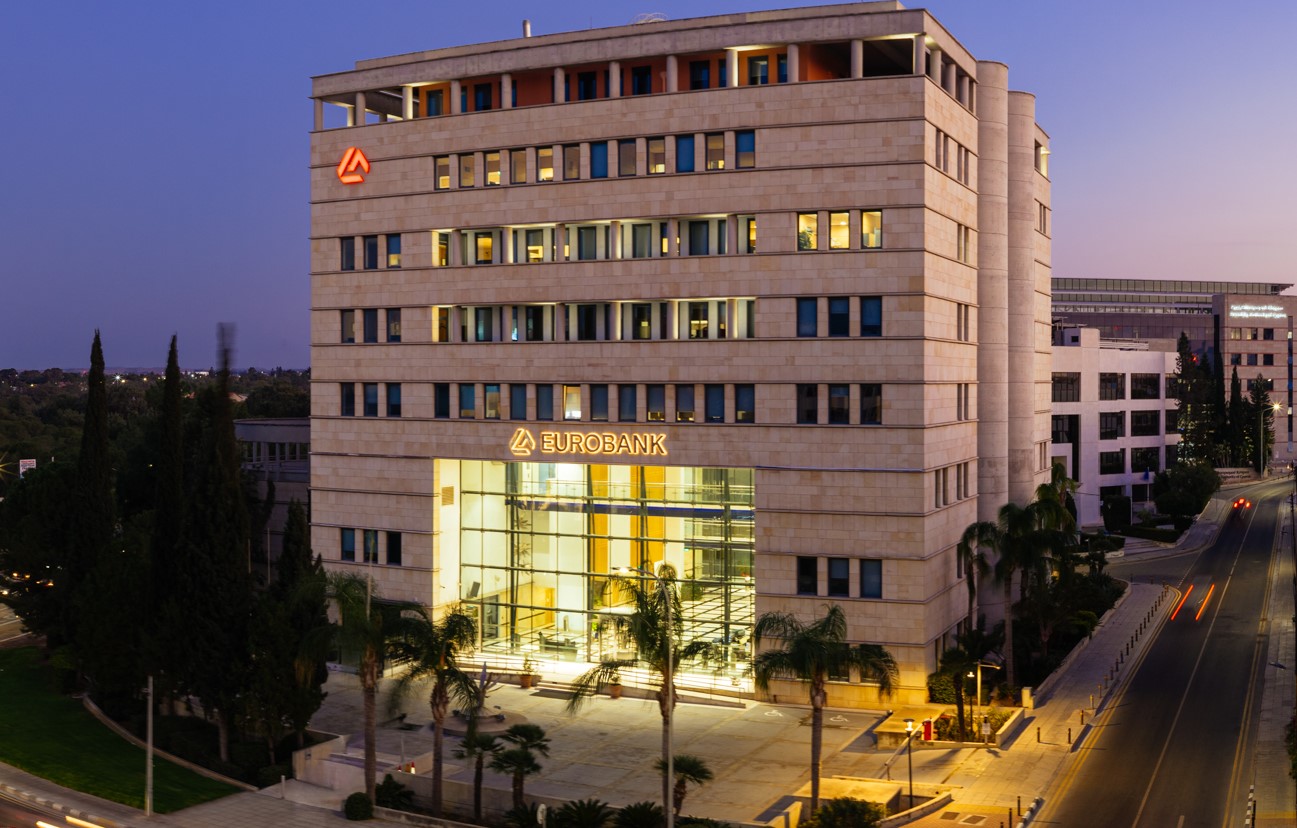
Moody’s turns positive on Eurobank deposits following Greek sovereign upgrade
Moody’s confirmed Eurobank’s Baa1 long-term deposit and senior unsecured debt ratings this week, while raising the outlook on its deposit ratings to positive from stable.
In its latest report, the findings of which were shared by Greek business outlet Newmoney, the ratings agency also confirmed the bank’s standalone Baseline Credit Assessment (BCA) and adjusted BCA at baa3, while changing the outlook on its senior unsecured debt to stable from negative.
The move followed Moody’s recent decision to raise the outlook on Greece’s sovereign rating to positive from stable while affirming the country’s Baa3 long-term issuer rating.
Moody’s said the confirmation of Eurobank’s Baa1 deposit and senior unsecured debt ratings reflected its baa3 standalone assessment and its view that potential losses if the bank were to fail would be very low, providing a two-notch uplift.
The agency continued to assess the likelihood of direct government support for the bank as low, meaning no additional rating uplift was applied on that basis.
Moody’s said Eurobank’s standalone credit profile was supported by strong and geographically diversified profitability, high asset quality and a healthy capital position.
However, the bank’s standalone assessment remains constrained by Greece’s Baa3 sovereign rating because of its exposure to the country’s sovereign risk.
The positive outlook on Greece’s rating creates upward pressure on Eurobank’s standalone assessment, while continued solid performance could further strengthen its credit profile.
Eurobank recorded a 16.6 per cent return on tangible equity in the first half of 2026, according to Moody’s, with profitability supported by a 13.5 per cent increase in fee and commission income and effective cost control.
The bank’s cost-to-income ratio, which measures how much it spends to generate income, stood at about 37 per cent.
Its operations in southeastern Europe, mainly through its subsidiaries in Cyprus and Bulgaria, accounted for 46 per cent of group net profit, strengthening the geographical diversification of its earnings.
Eurobank reported in July that it had generated €738 million in net profit during the first half of 2026, with its Cyprus operations contributing €231 million.
Adjusted net profit reached €776 million, an annual increase of 9.2 per cent, while earnings per share stood at €0.20 and return on tangible book value reached 16.6 per cent.
“Despite persistent geopolitical uncertainty and renewed tensions in the Middle East, the economies of our core markets have remained on a solid growth trajectory,” Eurobank chief executive Fokion Karavias said at the time.
He added that Greece’s economy had remained resilient, supported by investment activity, tourism and continued expansion in business lending.
“In Cyprus and Bulgaria, economic sentiment and growth remain also robust,” Karavias said.
Eurobank’s non-Greek operations generated €361 million in adjusted net profit in the first half, representing 46.5 per cent of group profitability.
The Cyprus operation generated adjusted net profit of €231 million, down 7.7 per cent from the first half of 2025, while Bulgaria’s adjusted net profit rose 7.8 per cent to €119 million.
Moody’s also highlighted Eurobank’s capital position, with its Common Equity Tier 1 ratio standing at 15.4 per cent in June 2026 on a pro forma basis.
That was well above the regulatory requirement of 10.7 per cent and the bank’s own 13 per cent target.
Moody’s said the level provided a sufficient buffer against potential losses, although deferred tax credits accounted for around 29 per cent of CET1 capital and therefore partly reduced its quality.
Asset quality also remained strong, with Eurobank’s non-performing exposure ratio falling to 2.5 per cent in June 2026, from 2.8 per cent a year earlier.
Limited new problem loans and provisions covering about 82 per cent of non-performing exposures supported the bank’s financial strength, while its cost of risk stood at 53 basis points, close to its target of 50 basis points.
The bank also had a comfortable liquidity and funding position, with net loans equal to about 66 per cent of deposits and its liquidity coverage ratio at 174 per cent.
High-quality liquid assets accounted for about 22 per cent of total assets in June 2026.
Eurobank’s minimum requirement for own funds and eligible liabilities, a measure of the loss-absorbing resources banks must maintain, stood at 31.3 per cent, above its 28 per cent target.
Moody’s said the positive outlook on Eurobank’s long-term deposit ratings was aligned with the positive outlook on Greece.
The agency said the sovereign rating currently represented the main constraint on a further improvement in Eurobank’s standalone assessment.
At the same time, Moody’s changed the outlook on senior unsecured debt to stable from negative.
This reflected its view that upward pressure from Eurobank’s standalone credit profile offset downward pressure associated with the expected implementation of the European framework for bank crisis management and deposit insurance.
A further upgrade could follow an improvement in Greece’s sovereign rating, provided Eurobank maintains resilient profitability and healthy asset quality over the next 12 to 18 months.
Moody’s said an upgrade of the bank’s senior unsecured debt was unlikely during the current outlook period, even if its standalone assessment improved.
It also considered a downgrade of long-term deposit ratings unlikely over the next 12 to 18 months given the positive outlook.
However, a significant deterioration in non-performing exposures or recurring profitability, together with a substantial weakening of capital, operating conditions or funding, could reduce the likelihood of an upgrade and put downward pressure on the senior unsecured debt rating.
A significant reduction in subordinated liabilities could also negatively affect the deposit and senior unsecured debt ratings.
Finally, the agency said Eurobank’s baa3 standalone assessment was two notches below its initial Financial Profile score of baa1, reflecting the constraint imposed by Greece’s sovereign rating and its expectation that the bank’s profitability and capital ratios would moderate from their currently strong levels.
Click here to change your cookie preferences