
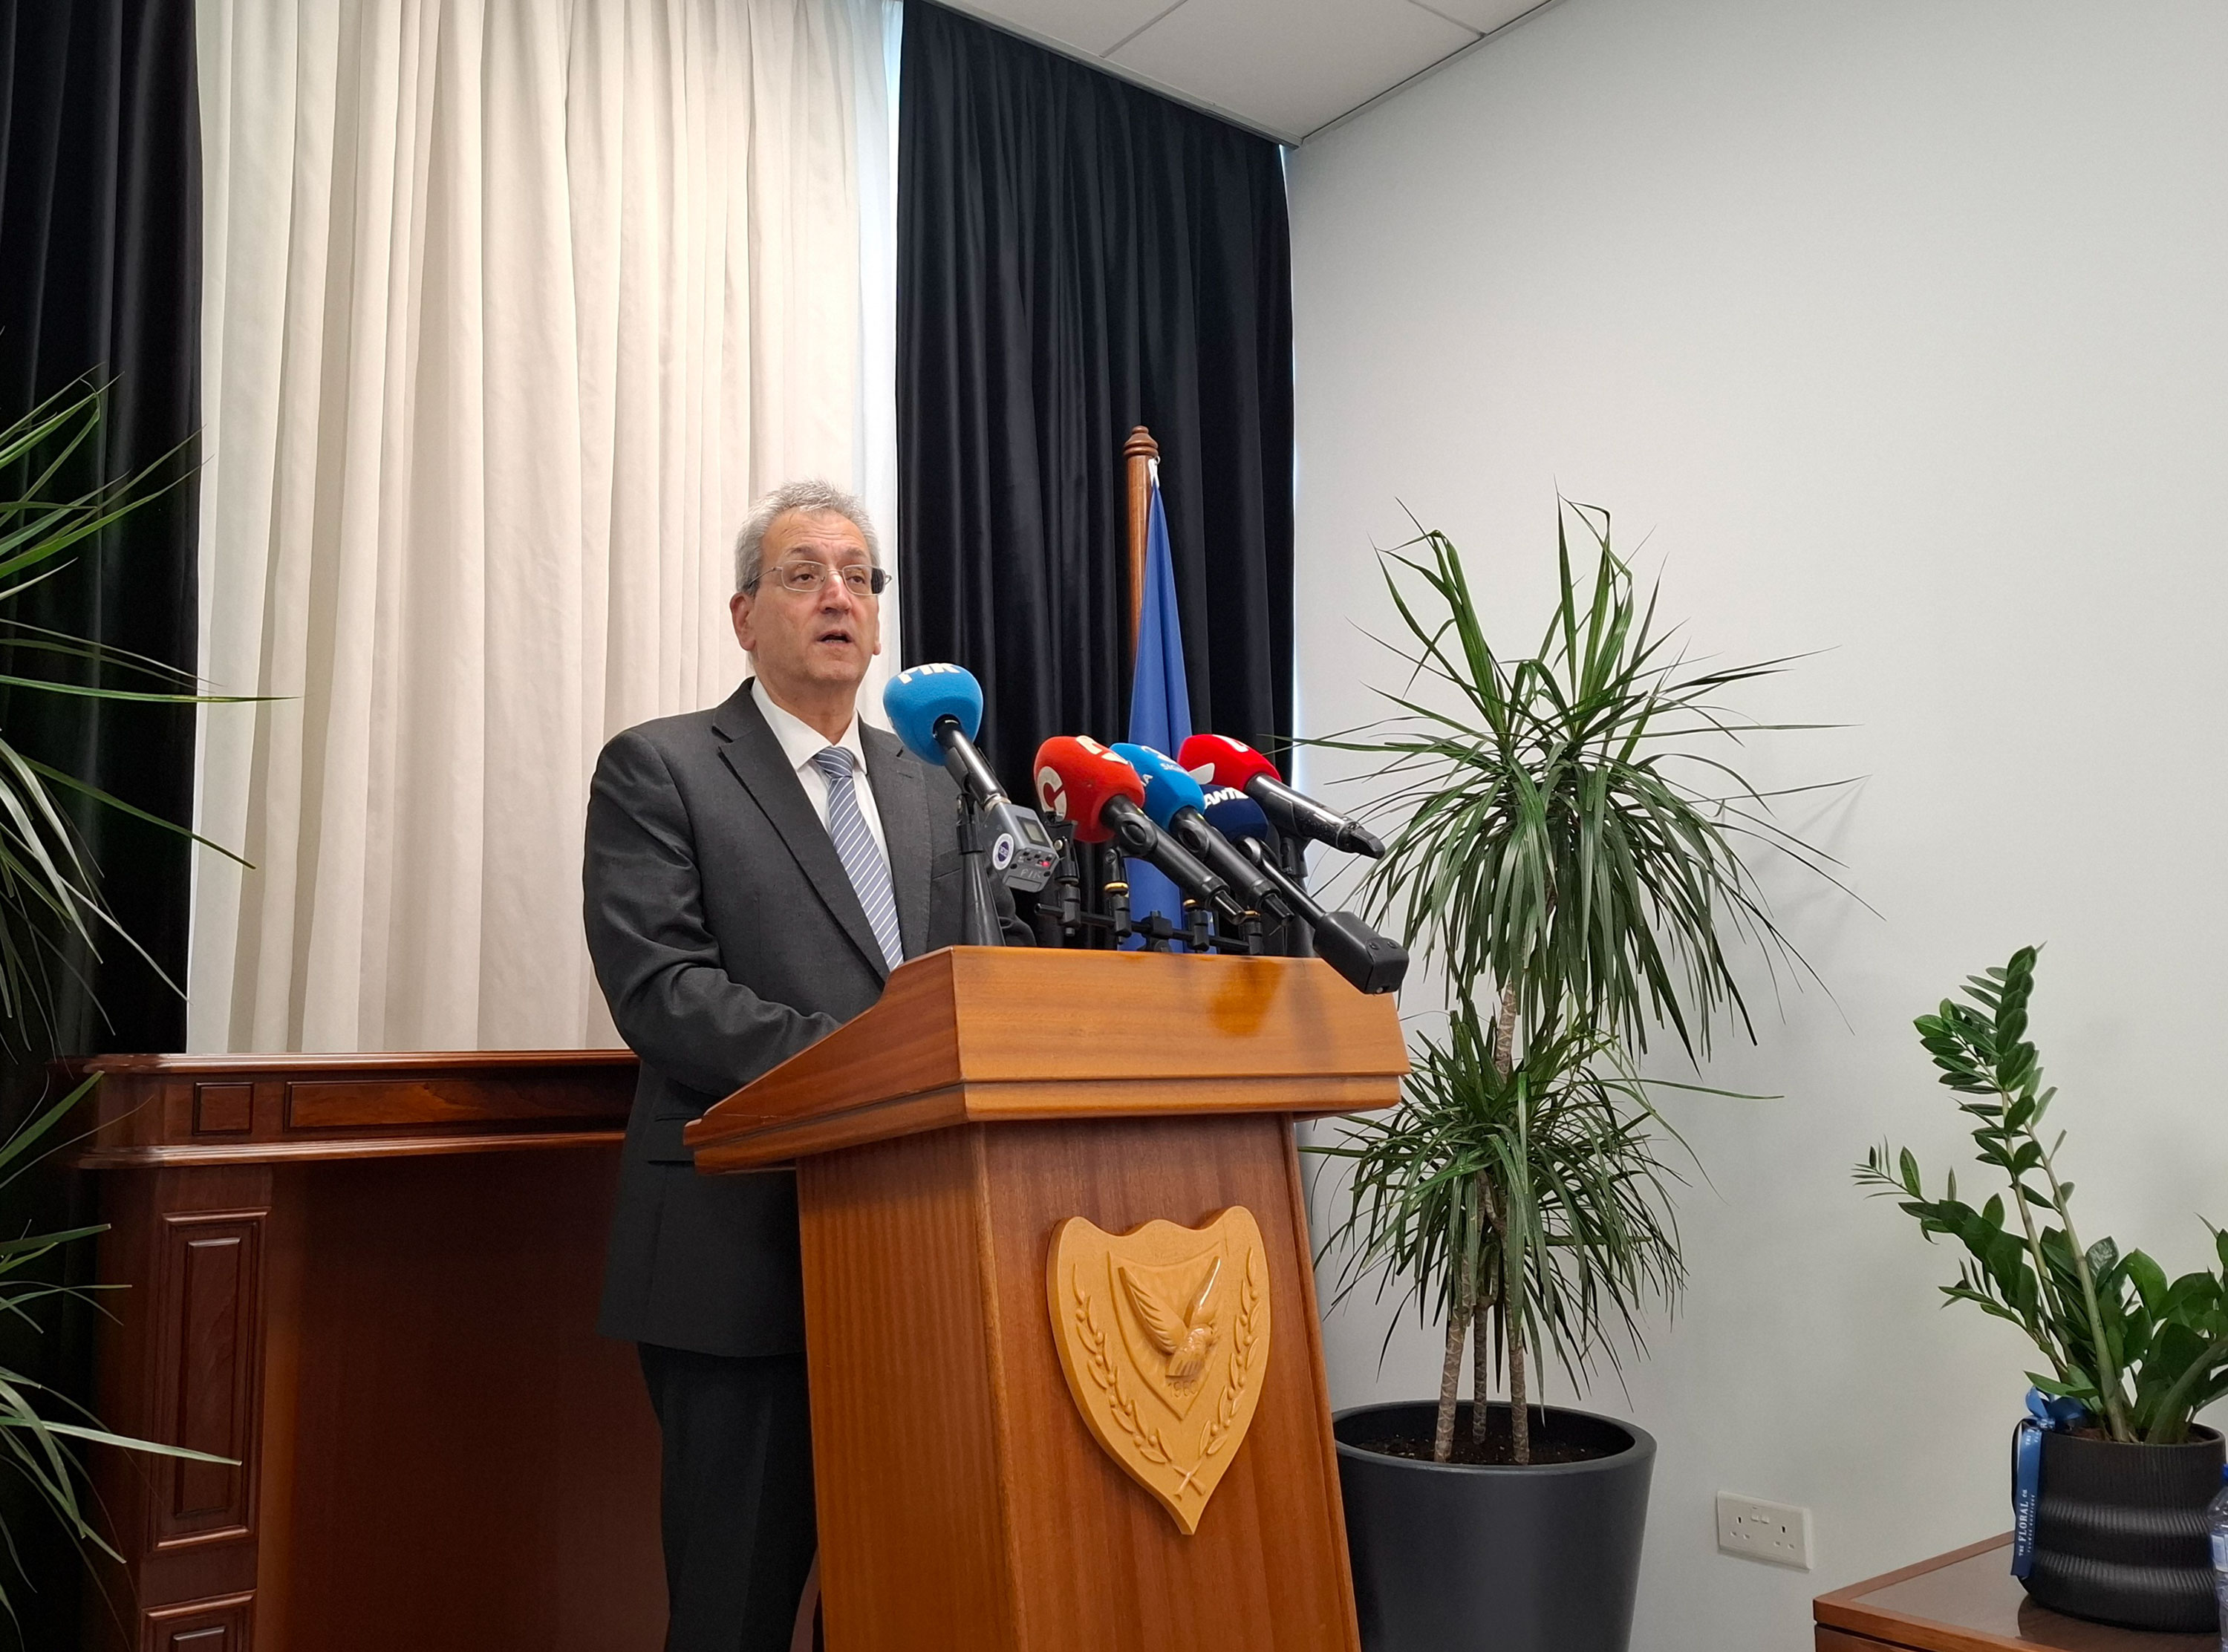
A gulf separates employers’ organisations and trade unions on the issue of provident funds and how they should fit into pension reform as a whole, Labour Minister Marinos Mousiouttas said on Thursday.
He was speaking to media after the latest meeting of the labour advisory aboard, which discussed provident funds for the first time.
The minister confirmed that trade unions want provident funds to be prescribed by law so that all private companies offer one, whereas employers insist they should remain voluntary.
In Cyprus, provident funds are based on collective or private agreements between employers and workers. No legislation exists mandating that companies provide a provident fund.
Having heard the two sides’ views on the matter, Mousiouttas said, the government would try to find the ‘sweet spot’.
The next meeting of the labour advisory board is scheduled for Friday, November 9.
The government’s general position, said the minister, is that provident funds “are a necessary institution, which supplements workers’ pensions.
“What we’ll try to do is see how this institution can be expanded.”
Stakeholders also discussed some of the details, such as how provident funds would be cashed out on retirement – whether as a lump sum or in instalments. Another issue is whether it would be possible to borrow from a provident fund, under certain conditions, as is the case today.
However, the minister clarified that sorting out the provident funds question “is not something that will happen today or tomorrow or even next year”.
In order for a provident fund to ‘mature’ and to yield, it takes at least a decade, he added.
Nevertheless, the talks would continue, and once the government brokers an agreement between trade unions and employers, the relevant bill would begin being drafted.
“For sure we will follow European standards,” Mousiouttas said of the future bill.
A provident fund is essentially a private group pension plan that some employers provide for their employees in Cyprus.
Provident fund members invest monthly a fixed percentage of their salary into a common investment pool for their retirement in much the same way as they would with social insurance.
A provident fund is managed by a licensed pension provider. The pension providers are typically either insurance companies or asset management companies.
The operation of a provident fund involves contributions from both the employee and the employer, similar to social insurance contributions. The amounts contributed by each party can either be identical or differ.
The employer usually sets the contribution amount and provides these details in an employment contract.
Employees are generally restricted from accessing their pension funds, before reaching their retirement age or unless their employment is terminated. However, it is permissible for the employee to borrow a portion of their funds.
Meanwhile the main thrust of pension reform – which includes pillars zero and one – is still being worked on by the government.
The draft legislation needs to be vetted by the attorney-general’s office.
Once that is done, said Mousiouttas, he would present the bill to the cabinet. Once the cabinet gives the nod, the bill would be tabled to parliament.
Pillar zero, as it is called, concerns pensions for low-income earners.
Pillar one involves a reworking of the mechanics of the Social Insurance Fund, along with state pensions.
Provident funds and occupational pension schemes fall within pillar two.
The government aims to roll out pillars zero and one of pension reform at the beginning of 2027.
Click here to change your cookie preferences