
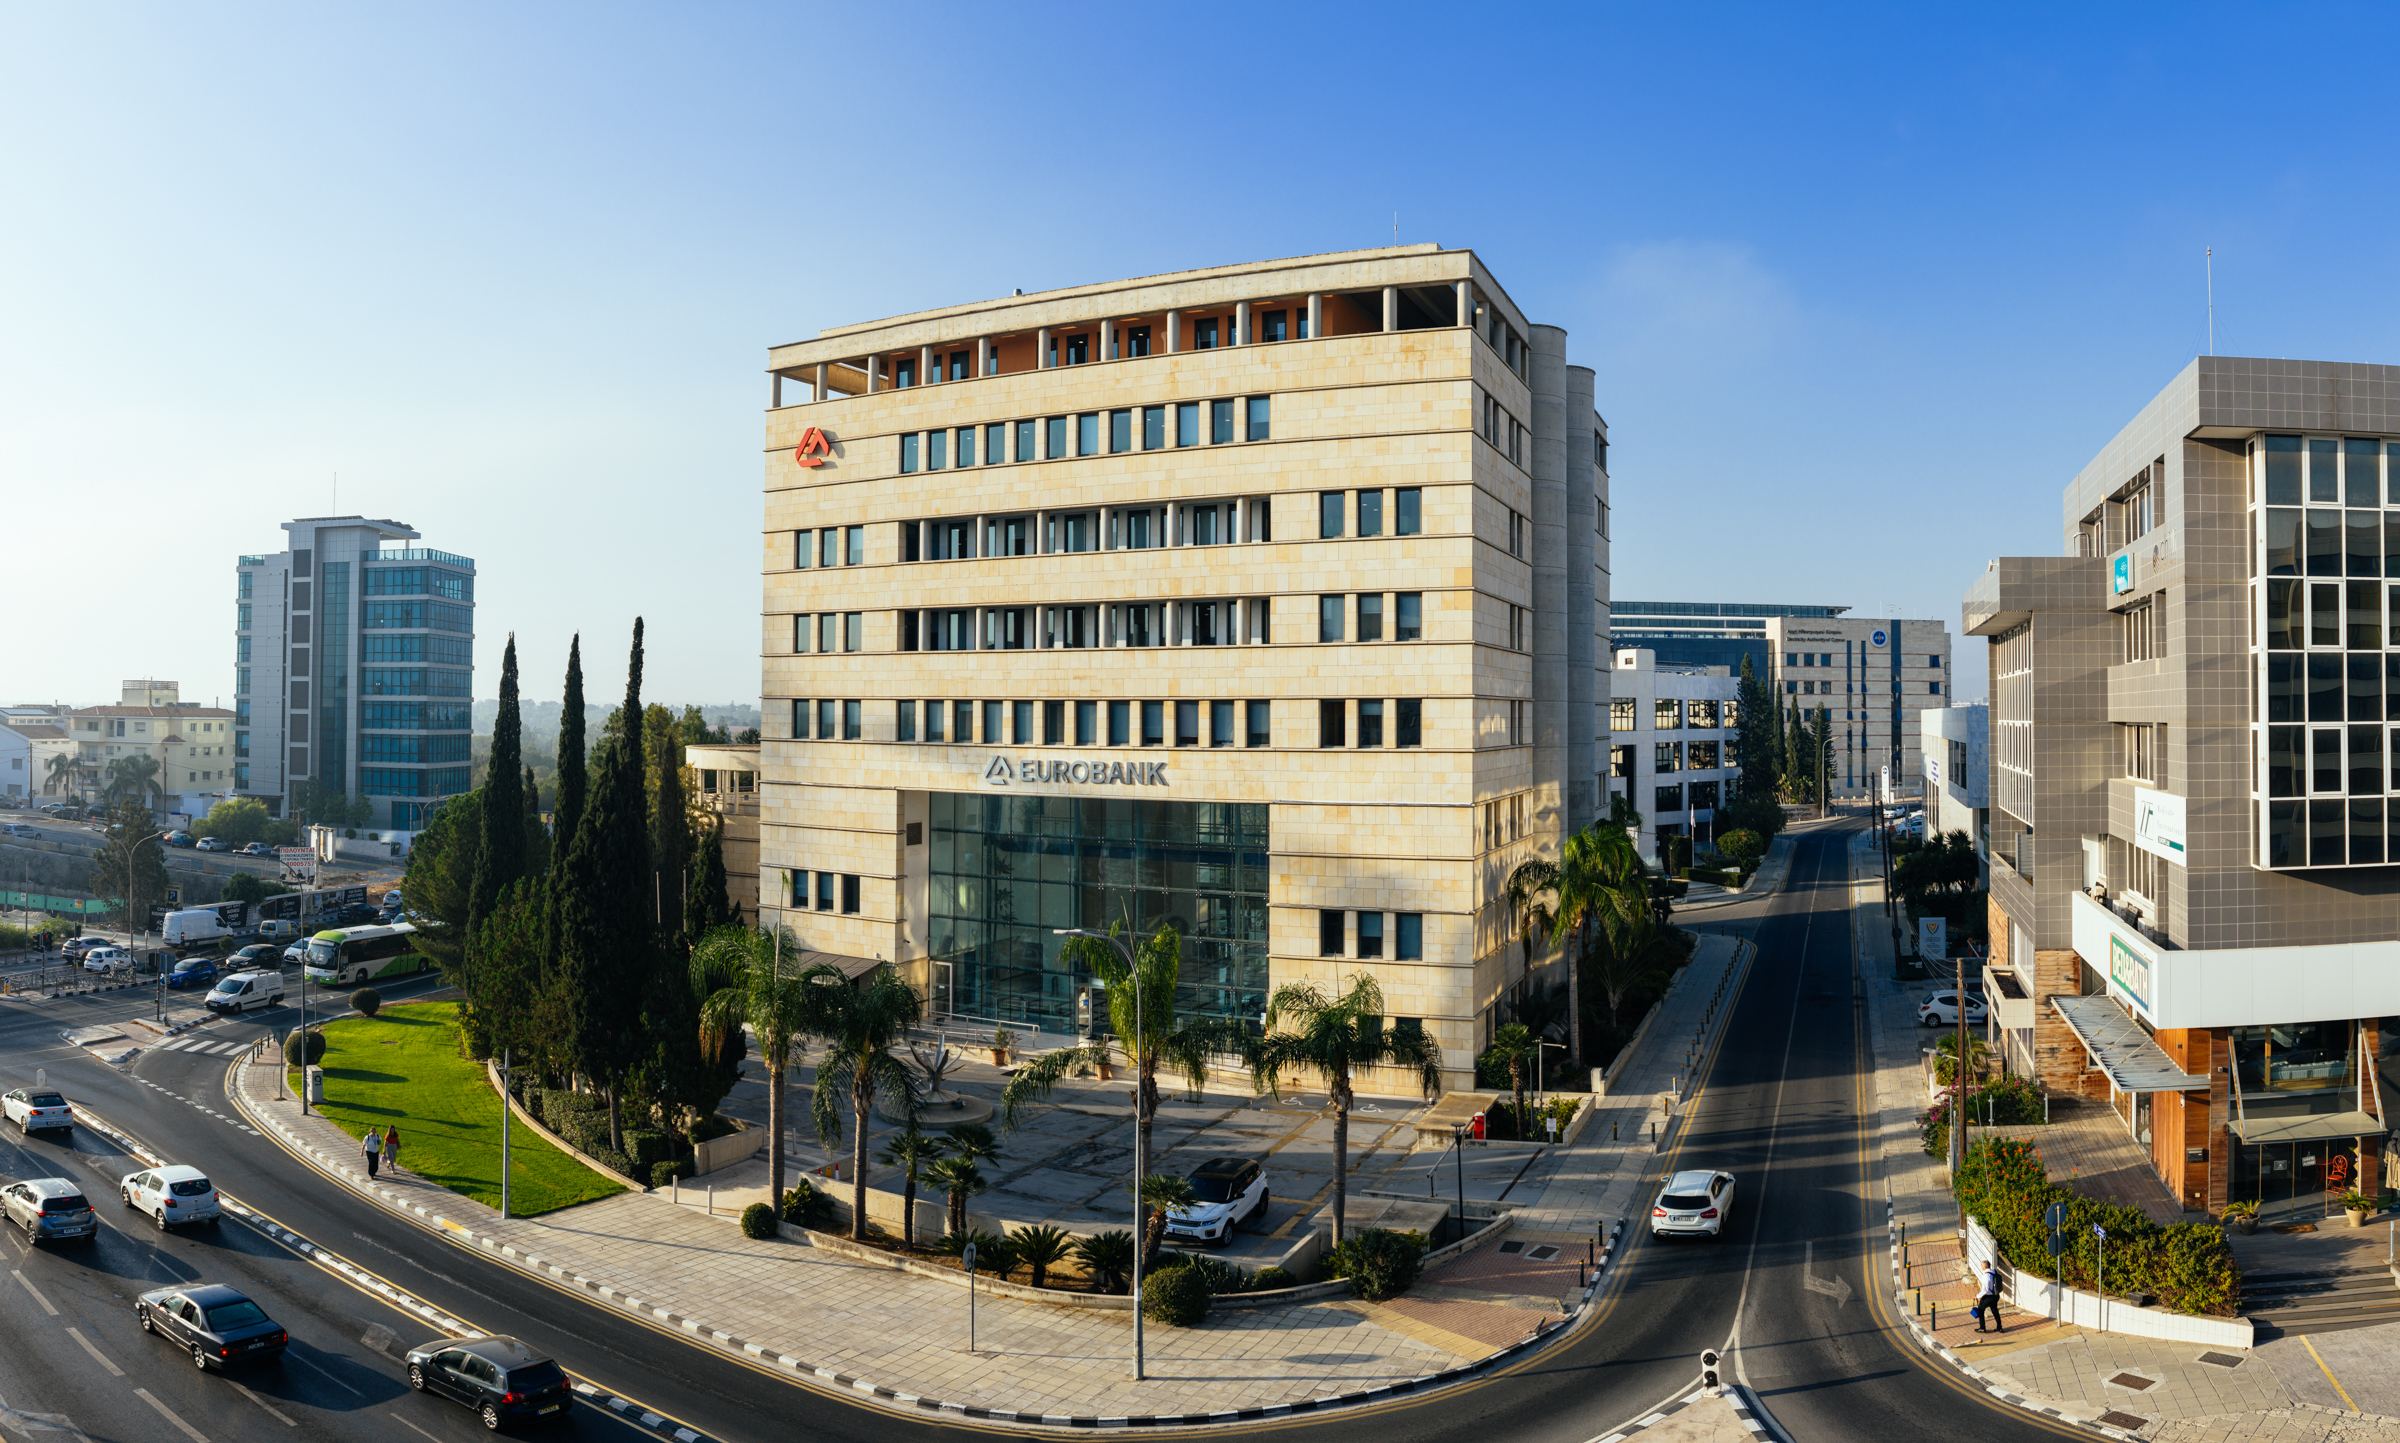
The strong contribution of Cyprus and Bulgaria to Eurobank’s earnings, alongside a potential rise in non-performing loans in the final quarter of 2026, has been highlighted by credit rating agency Morningstar DBRS in its assessment of the Greek lender’s third-quarter results.
Activities outside Greece accounted for 46 per cent of Eurobank’s adjusted net profits, with Cyprus and Bulgaria identified as the main contributors, according to the agency.
Morningstar DBRS also warned that non-performing loans (NPLs) could increase in the fourth quarter of 2026, as loans affected by legislation concerning the conversion of Swiss franc-denominated loans may be reclassified as unlikely to pay.
Such a development could add around 40 basis points to the NPL ratio and reduce the bank’s NPL coverage ratio by 10 percentage points, the agency said.
The assessment comes as Eurobank reported higher earnings and improvements across several key financial indicators during the first nine months of 2026.
The bank’s net profits increased by 12 per cent year-on-year, while adjusted net profits rose by 14 per cent over the same period.
Its return on tangible equity reached 16.9 per cent, reflecting the bank’s profitability during the period.
Net interest income increased by 8.7 per cent year-on-year, supported by growth in the loan portfolio and continued assistance from interest rates.
Meanwhile, net fee and commission income rose by 13 per cent, while the cost-to-income ratio improved to approximately 36 per cent during the first nine months of 2026, compared with around 37 per cent in the corresponding period of 2025.
Eurobank’s customer deposits grew by almost 11 per cent year-on-year, exceeding €87 billion, in line with developments in its lending activity.
At the end of September 2026, the bank’s loans-to-deposits ratio stood at 66.4 per cent, while its liquidity coverage ratio reached 174.4 per cent, indicating its liquidity position.
Its Common Equity Tier 1 (CET1) capital ratio stood at 15.5 per cent, or 14.3 per cent following the acquisition of Eurolife.
Morningstar DBRS said the capital ratio remained comfortably above both the bank’s overall capital requirement of 10.7 per cent and its internal target of 13 per cent.
The figures underline Eurobank’s profitability and capital position, while the agency’s comments point to the potential impact of the Swiss franc loan reclassification on asset quality in the final quarter.
Click here to change your cookie preferences