
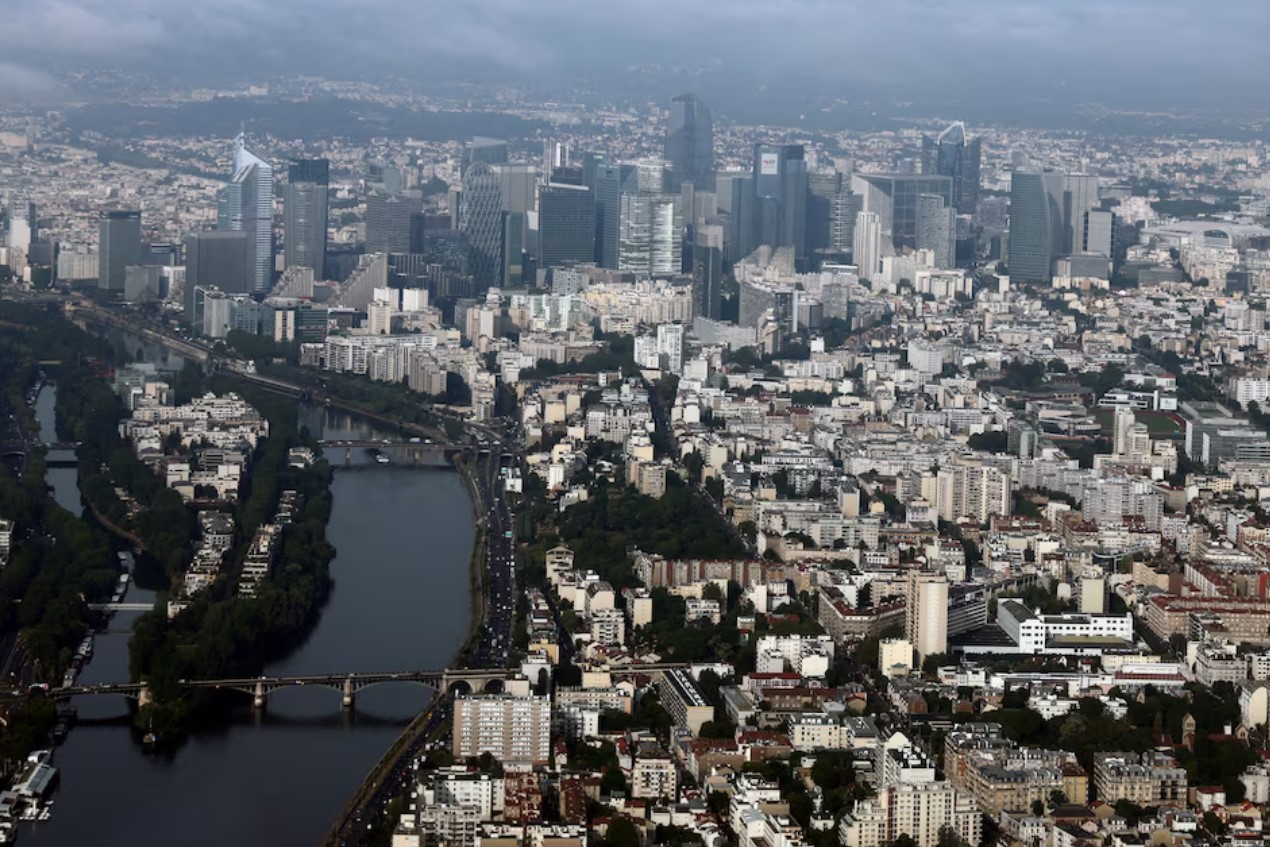
France is not facing an immediate risk of a public debt crisis comparable to the eurozone turmoil of the 2010s, but persistent deficits, weak economic growth and rising borrowing costs pose significant longer-term risks, Eurobank has warned in a report examining the country’s fiscal outlook ahead of its 2027 presidential election.
In its report, titled “France: Presidential elections complicate fiscal consolidation”, Eurobank argues that the country’s deteriorating public finances primarily reflect structural weaknesses, rather than cyclical factors.
“France’s fiscal deterioration primarily reflects structural weaknesses and, to a lesser extent, cyclical factors,” the report states.
France is struggling to finance an expensive economic and social model against a backdrop of low potential growth and an already high tax burden, the bank says.
“Restoring fiscal sustainability therefore requires a combination of systematic control of public spending, reforms to the pension system and public administration, as well as measures to strengthen productivity, employment and investment,” Eurobank emphasises.
The bank nevertheless identifies several factors that limit the immediate risk of a sudden funding crisis, including the size and diversity of the French economy, its broad tax base, the relatively long average maturity of its public debt and the strengthened European financial stability framework.
However, persistent primary deficits, sluggish growth and rising borrowing costs represent a significant medium-to-long-term risk, with potential consequences for the wider eurozone.
Eurobank argues that France’s central challenge extends beyond reducing its budget deficit in the short term, requiring a structural adjustment of its economic and social model to bring it into line with the country’s long-term growth potential and fiscal constraints.
The country’s underlying fiscal difficulties stem from a combination of persistently high public spending that is difficult to reduce, low potential economic growth and limited scope to increase tax revenues further.
These pressures are compounded by political uncertainty ahead of the presidential election scheduled for spring 2027 and the fragmentation of political forces in the National Assembly, which make it harder to implement a coherent fiscal consolidation strategy, the report adds.
Despite its high tax burden, France continues to record substantial budget deficits while its public debt keeps rising.
Citing the government’s draft budget for 2027, Eurobank expects the deficit to narrow from 5.4 per cent of gross domestic product (GDP) in 2026 to 5 per cent in 2027.
At the same time, public debt is projected to rise from 119.3 per cent of GDP to 121.7 per cent, a level more than twice the ratio recorded in 2000.
“Consequently, even the full implementation of the planned fiscal adjustment measures would not be sufficient to stabilise the debt,” the report warns.
The bank’s assessment suggests that, although France retains important economic and institutional safeguards against an immediate financing crisis, addressing its debt trajectory will require more than short-term deficit reduction.
Sustained fiscal consolidation, structural reforms and measures to improve productivity, employment and investment will be needed to address the underlying imbalances and reduce the risk of further deterioration in public finances.
Click here to change your cookie preferences