
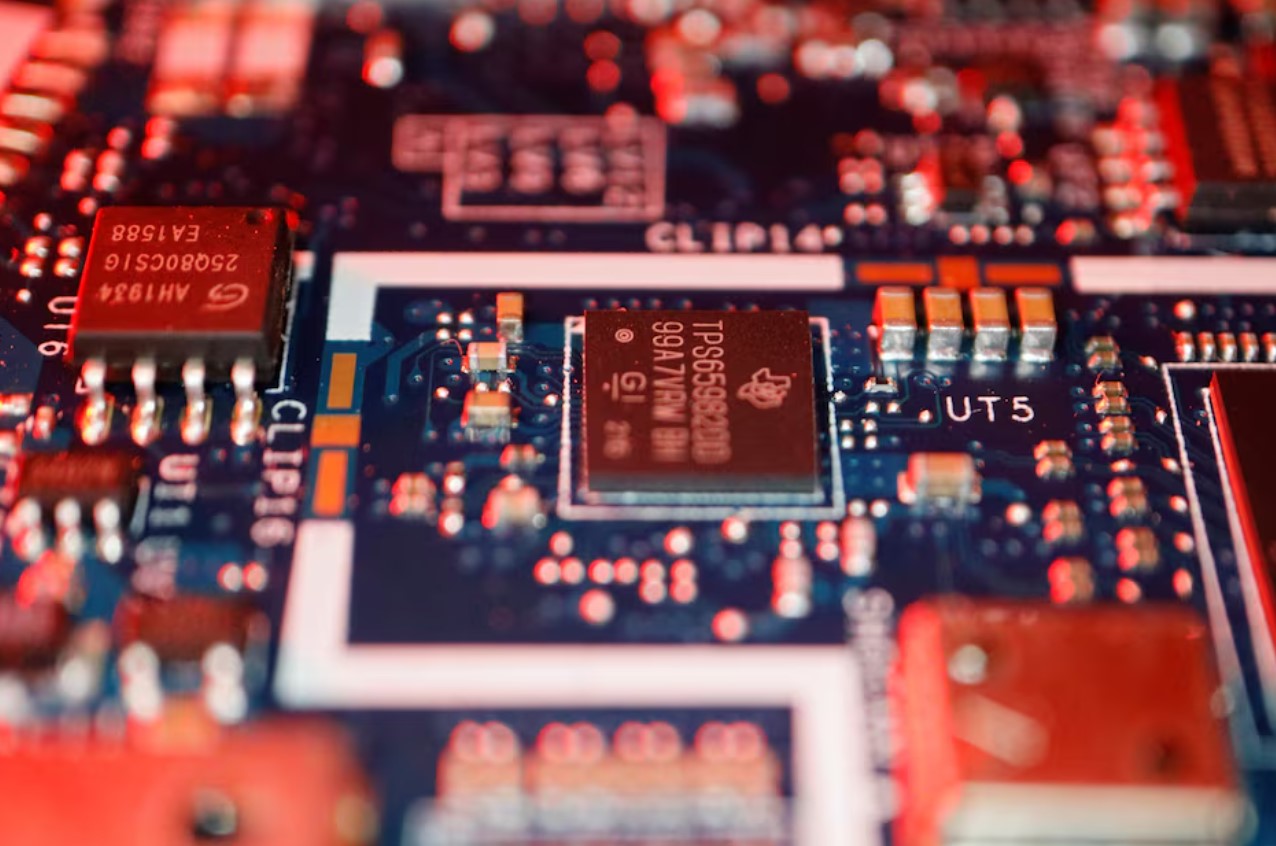
AI chip boom could push up prices of electronics
Global semiconductor revenue surged to a record $425 billion in the second quarter of 2026, with the unprecedented growth in memory chips driven by artificial intelligence demand expected to feed through to prices for a wide range of electronic devices.
Research from market intelligence firm Omdia showed semiconductor revenue increased by a record 31.4 per cent quarter-on-quarter in the second quarter, surpassing the previous record of 29.2 per cent recorded in the first quarter.
The surge took semiconductor revenue for the first half of 2026 to $752 billion, putting the industry on track for another year of exceptional growth.
The implications extend well beyond chip manufacturers because semiconductors are essential components in products ranging from gaming consoles and PCs to smartphones, servers, cars and a wide range of consumer electronics.
Higher chip prices can therefore feed through to manufacturers’ costs and, depending on supply conditions and pricing strategies, eventually contribute to higher prices for consumers buying electronic devices.
Memory is currently the biggest driver of the increase, with strong AI demand prompting chip manufacturers to redirect production towards the components required by increasingly sophisticated AI systems.
This shift is affecting the balance between supply and demand and pushing up average selling prices and revenue across the memory market.
Memory integrated circuits accounted for more than half of all semiconductor revenue in the second quarter.
The memory market is led by dynamic random-access memory (DRAM) and NAND flash, both of which are heavily used in computers, smartphones, servers and other electronic equipment.
DRAM, NAND and NOR chips each recorded their highest sequential growth for a second quarter since Omdia began tracking the market.
All three types also reached their highest recorded quarterly revenue in the second quarter.
The scale of the increase is particularly striking by historical standards.
Since Omdia began tracking the semiconductor market in the first quarter of 2002, only 10 of 97 quarters have recorded sequential revenue growth of more than 10 per cent.
The past four quarters, beginning in the third quarter of 2025, have all recorded double-digit sequential growth.
Omdia expects the third quarter of 2026 to continue that trend.
The effect of AI is also extending beyond memory chips, with other semiconductor components recording growth well above normal seasonal patterns.
The wider semiconductor market excluding memory grew by more than 10 per cent quarter-on-quarter in the second quarter.
That compares with typical second-quarter sequential growth of only slightly more than 3 per cent for non-memory semiconductors, based on Omdia data covering 2002 to 2025.
Microprocessor revenue increased by 16 per cent quarter-on-quarter in the second quarter as microprocessors play an increasingly important role in AI infrastructure.
That growth was substantially above the component’s typical seasonal growth of 1 per cent.
The figures illustrate why the current semiconductor cycle could have consequences across the technology industry.
When demand for AI infrastructure absorbs more of the world’s available chip production, manufacturers of other devices can face higher component costs or tighter supplies, potentially affecting the prices and availability of products further down the supply chain.
For consumers, that can mean that the cost of building or upgrading a gaming PC, buying a smartphone or purchasing other electronics is affected by developments taking place far upstream in semiconductor manufacturing.
The impact is not necessarily uniform, however, as manufacturers can absorb higher component costs, renegotiate supply contracts, alter specifications or pass some or all of the increase on to customers.
The semiconductor boom is nevertheless already large enough to put the industry’s overall revenue on a record trajectory.
Revenue exceeded $750 billion during the first half of 2026, already surpassing the full-year total recorded in every year except 2025.
Omdia forecasts that semiconductor revenue will exceed $500 billion in the third quarter, taking cumulative revenue for the first nine months of 2026 above $1.25 trillion.
That would put the first three quarters of 2026 alone at a level 50 per cent higher than semiconductor revenue for the whole of 2025.
Omdia expects the strong market conditions and record quarterly revenue levels to continue, with AI demand remaining a major factor shaping production priorities and pricing across the semiconductor industry.
Click here to change your cookie preferences