
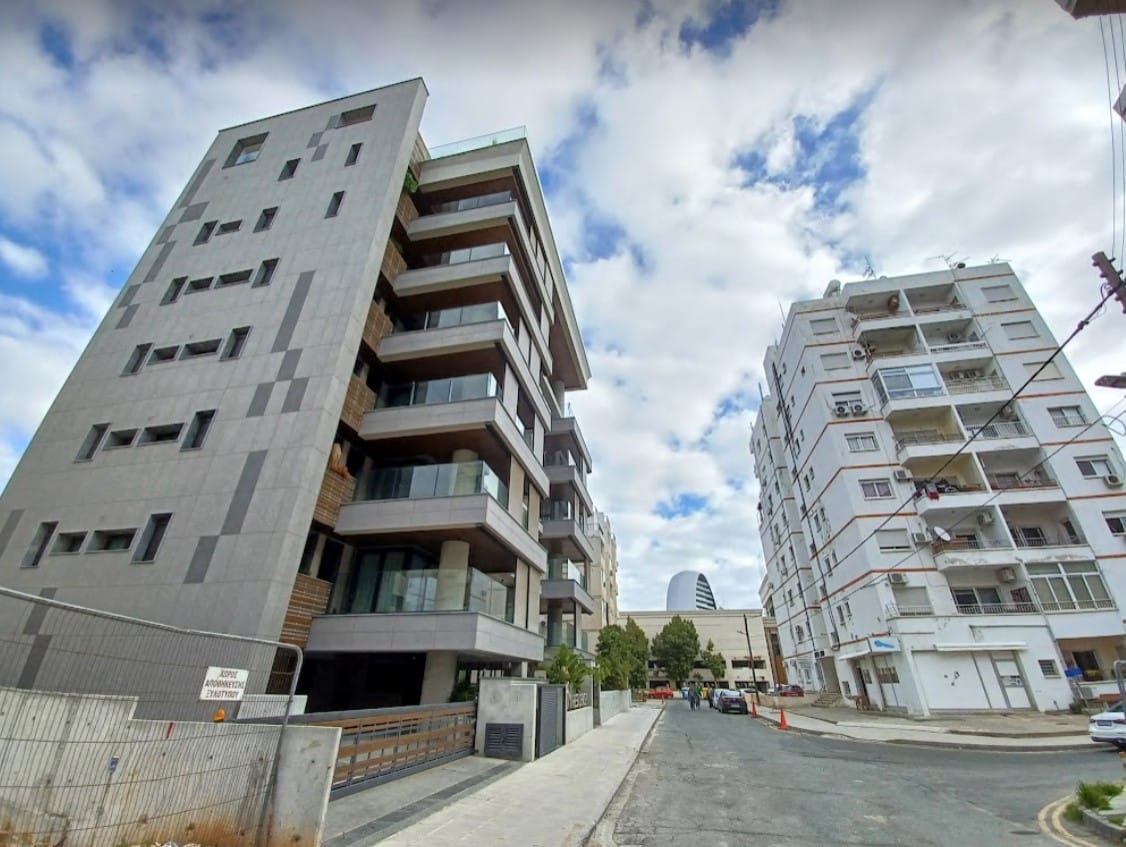
Nicosia offers hope as Limassol property market shuts the door on average earners
Only 1.8 per cent of two- and three-bedroom apartments advertised for sale in Limassol are priced within the estimated €256,000 budget of a hypothetical average-income household, according to a new study by real estate analytics firm Ask Wire.
The analysis, based on residential property listings across the government-controlled areas of Cyprus, highlights wide differences in housing affordability between districts, with Nicosia offering the greatest overall choice of apartments within the study’s assumed budget.
The research compares asking prices advertised on online marketplace Bazaraki in early October with household purchasing power calculated using median salary data from the Cyprus Statistical Service.
Ask Wire examined 25,550 active property listings after carrying out data validation checks, of which 17,532 were for two- or three-bedroom homes.
The study identifies two main obstacles to homeownership, namely the ability to raise the initial deposit required for a mortgage and the capacity to meet monthly repayments.
To establish a benchmark, the company modelled a household with two working adults and two dependent children, with each adult earning the estimated median salary.
Assuming the household had no other outstanding loans and could secure a mortgage at an interest rate of 3.24 per cent over 25 years, its combined gross monthly income would be approximately €4,503, while net income would stand at €3,988.
If 25 per cent of net monthly income were allocated to mortgage repayments, the household could afford a monthly instalment of around €997 and a property costing up to €255,995.
Such a purchase would require an initial equity contribution of €51,199, equivalent to a 20 per cent deposit, before additional property purchase expenses.
Ask Wire stressed that the 25 per cent repayment threshold was an assumption used for its analysis, rather than a limit imposed by the Central Bank of Cyprus or a guarantee that a bank would approve a mortgage.
The findings show that Nicosia is the most affordable district overall, with 59.6 per cent of two- and three-bedroom apartments within the €256,000 threshold.
Famagusta follows closely at 58.6 per cent, while the corresponding share in Larnaca stands at 48.1 per cent.
The picture is considerably more restrictive in Paphos, where just 9.6 per cent of apartments fall within the budget, and particularly in Limassol, where the figure drops to 1.8 per cent.
The differences become clearer when the figures are broken down by property size.
In Nicosia, 869 of the 1,226 advertised two-bedroom apartments, or 70.9 per cent, were priced at up to €256,000.
The equivalent figure in Famagusta was 225 out of 386 properties, or 58.3 per cent, while Larnaca had the highest absolute number of affordable two-bedroom apartments, with 1,097 out of 2,105 listings, representing 52.1 per cent.
In Paphos, 141 of 1,146 two-bedroom apartments were within the budget, equivalent to 12.3 per cent.
Limassol had just 111 affordable properties among 4,294 two-bedroom apartment listings, or 2.6 per cent.
For three-bedroom apartments, Famagusta had the highest proportion of affordable options, at 60 per cent, although this represented only 48 of 80 listings.
In Nicosia, 247 of 647 three-bedroom apartments were priced within the threshold, or 38.2 per cent, while Larnaca had 135 affordable properties out of 456, equivalent to 29.6 per cent.
The situation was markedly more difficult in Paphos, where just three of 348 three-bedroom apartments were within budget, representing 0.9 per cent.
In Limassol, only seven of 2,376 three-bedroom apartment listings met the affordability criteria, or 0.3 per cent.
Detached houses are even less accessible in most districts, particularly for households seeking three bedrooms.
Among two-bedroom houses, Nicosia had 22 affordable properties out of 26 listings, representing 84.6 per cent.
Larnaca followed with 78 out of 151 properties, or 51.7 per cent, while Famagusta had 22 affordable homes among 63 listings, equivalent to 34.9 per cent.
In Paphos, 26 of 130 two-bedroom houses were within budget, representing 20 per cent, while Limassol had 22 affordable properties out of 235, or 9.4 per cent.
The figures were considerably lower for three-bedroom houses.
Nicosia had 65 affordable properties among 480 listings, or 13.5 per cent, while Larnaca had 52 out of 733, representing 7.1 per cent.
In Famagusta, 21 of 376 three-bedroom houses were priced within the threshold, equivalent to 5.6 per cent.
Paphos had 17 affordable properties among 993 listings, or 1.7 per cent, while Limassol had just 16 out of 1,279, representing 1.3 per cent.
Ask Wire chief executive Pavlos Loizou said the figures pointed to three main conclusions, beginning with the widening gap between property prices and the purchasing power of salaried workers in Limassol.
“The problem in Limassol is not a lack of supply, but the rapidly widening gap between property prices and the purchasing power of salaried workers,” Loizou said.
He highlighted that only 111 of the 4,294 two-bedroom apartments advertised in the district were within the modelled household’s budget, while just seven of the 2,376 three-bedroom apartments met the same criteria.
Additionally, Loizou said that the Cypriot capital offered the most favourable ratio for buyers, with 869 of its 1,226 two-bedroom apartments considered affordable.
However, he pointed out that Larnaca had the largest number of affordable two-bedroom apartments, with 1,097 properties falling within the price threshold.
His third conclusion concerned the growing difficulty of buying a detached house, particularly one with three bedrooms.
“Regardless of district, purchasing a detached house, particularly one with three bedrooms, is tending to become a luxury,” he said.
Even in Nicosia, only 65 of the 480 advertised three-bedroom houses were within the budget, while the equivalent figures were 17 in Paphos and 16 in Limassol, Loizou said.
The study also highlights the importance of having sufficient cash available for a deposit, rather than relying solely on household income.
If a household had €40,000 in available funds, after allowing for expenses and retaining a financial reserve, its overall property purchase budget would fall to €200,000, according to Ask Wire.
The company said that while other assets could theoretically strengthen a household’s equity contribution, owning assets did not necessarily mean having immediate access to liquid funds.
For banks, developers and policymakers, the findings point to the need to consider the purchase price, initial capital requirement and monthly mortgage repayment together, rather than treating affordability as a question of income alone.
Ask Wire said the results highlighted the need for targeted housing measures and financial products tailored to the available property supply and household circumstances in each district.
The company cautioned that the salary figures used in its model were estimates and that the household scenarios were hypothetical.
Moreover, the research did not establish how many families would actually qualify for a mortgage, as this would require an individual assessment of income, living expenses, existing financial commitments and available capital.
It also stressed that advertised asking prices do not necessarily reflect final transaction prices or confirm that properties remain available for purchase.
Click here to change your cookie preferences