
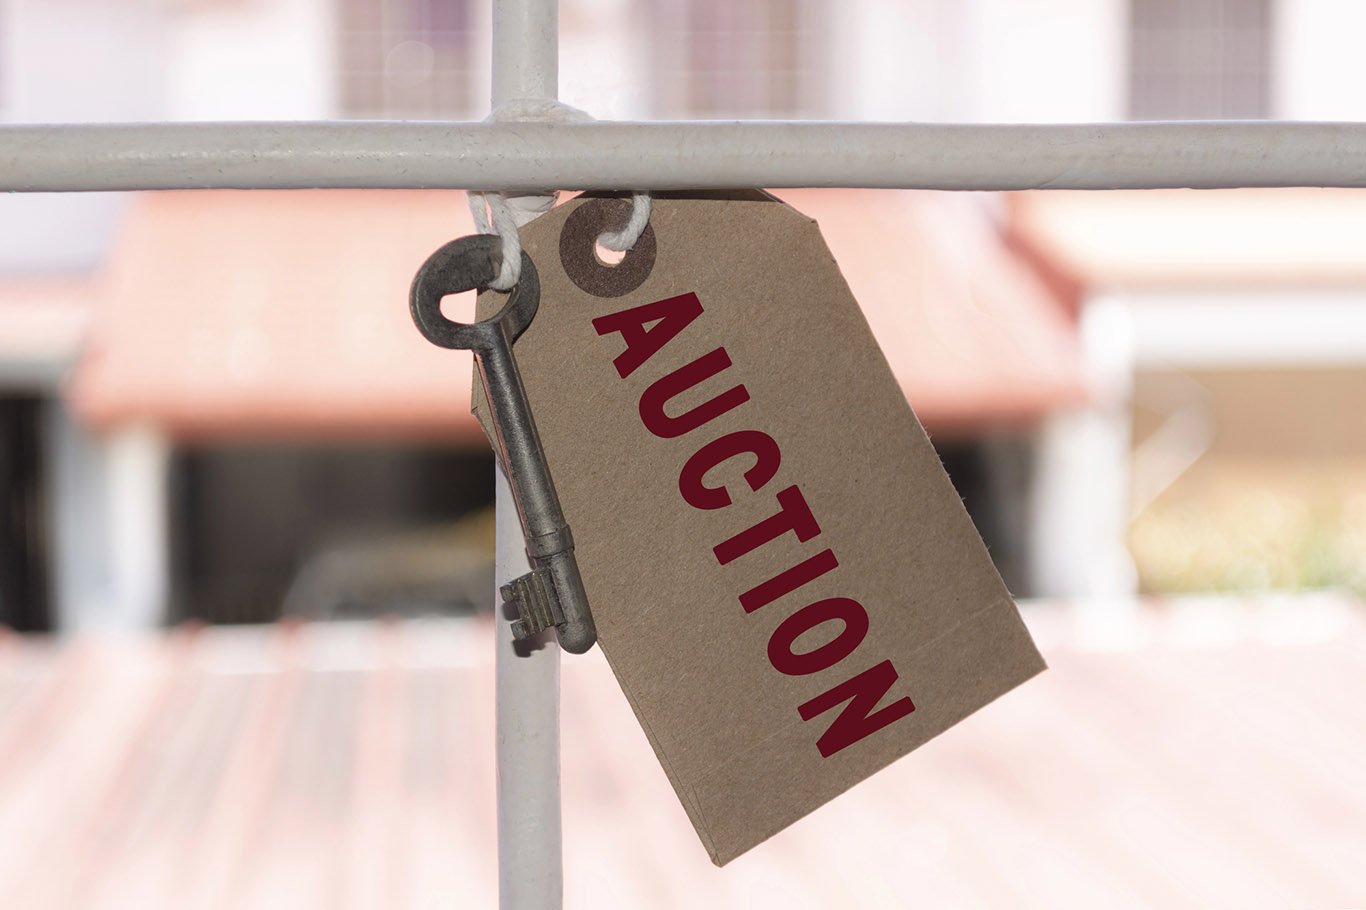
The retired homeowners say a loan originally worth about €187,000 has become a claimed debt of €400,000
Still haunted by their decision some 20 years ago to take out a mortgage denominated in Swiss francs, a distressed couple from Britain are on the verge of losing their Limassol home to lenders, their residence slated for auction by the end of the year. They were among thousands of Britons lured by the Cyprus property dream, only to get stung by the loan scheme during the 2000s.
The couple, who did not wish to be identified, reached out to the Cyprus Mail, hoping to generate publicity as they say that the credit-acquiring company, which now owns their mortgage, refuses to budge despite being made a reasonable offer to settle the outstanding debt.
“This is our only residence, we’ve been living there for the last 20 years. Losing it would be devastating,” said John Taylor (not his real name), a 67-year-old pensioner.
He added: “We like Cyprus, we don’t want to leave.”
Between 2003 and 2010, Cypriot banks heavily marketed loans denominated in Swiss francs because the interest rates were lower, but this backfired spectacularly when the franc soared after the financial crisis, and mortgage repayments doubled.
Lawyers say the banks often failed to explain the potential risks of currency fluctuation that could cause repayments to rise, and also applied heavy interest rate rises.
For example, from 2011 to 2014 the Swiss franc strengthened by 35 per cent, and because the contracts did not peg the franc to the euro, the fluctuation inflated mortgage repayments.
The cost of a cheaper loan
The ‘hook’ was the low interest, drawing in unsuspecting punters. Frequently these were interest-only mortgages, where the monthly payments cover only the interest charged on the borrowed amount (the principal), rather than paying down the actual debt.
Because borrowers were not chipping away at the principal balance, their monthly payments were initially lower than a standard capital-repayment mortgage.
On the flipside, the amount originally borrowed did not decrease over the course of the interest-only period.
And at the end of the mortgage term, debtors still owed 100 per cent of the original loan and must repay it in a single lump sum.
The risk is that no equity is built from the monthly payments.
This was the type of interest-only loan taken out by John and his wife back in 2006.
Like many others, they say they were mis-sold the mortgage, with the lender (Alpha Bank) not bothering to explain the possible risks from exchange-rate fluctuations.
“What began as a loan of approximately €187,000 has, following the Swiss-franc crisis and the way the loan was calculated, grown into a claimed debt of around €400,000,” John told us.
“We believe this is deeply unfair. An independent forensic report prepared by our accountant puts the legitimate debt at approximately €178,000, a substantial difference from the amount now claimed.”
This is borne out by the report, seen by the Cyprus Mail.
The loan is now being handled by Sky CAC Limited, previously Alpha Bank, through its servicer doValue Cyprus.
Meanwhile, the Taylors’ home is scheduled for electronic auction on December 29.
Settlement offer rejected
What makes this particularly distressing, said John, is that they’re not simply refusing to pay.
The couple have two UK property sales progressing, and they expect the proceeds to provide the funds for a settlement of approximately €255,000 by February 2027.
Nevertheless, doValue has told their lawyer that it will not consider a settlement proposal without an immediate payment of €30,000.
“We are therefore facing the possible loss of our home of 20 years just weeks before we expect to have the means to resolve this matter. We are retired and live on pensions, and the prospect of losing our home at our age is devastating.”
John said they also tried to obtain assistance under the government’s Rent Against Instalment scheme, but their application was denied because they did not receive qualifying public assistance during the specified period.
“We’re asking a straightforward question: why can a settlement based on substantial forthcoming funds not be properly considered, with the auction postponed until February 2027, rather than proceeding with the sale of our only home?”
“We appreciate that the lender has its own position and that it should have an opportunity to respond. However, we believe our case deserves independent scrutiny, particularly in light of the longstanding problems experienced by Swiss-franc mortgage borrowers in Cyprus.”
Thousands caught by Swiss-franc loans
Looking at media reports from 2008 onward, it appears that thousands of Britons got caught up in this conundrum. In 2013 The Guardian cited a London-based solicitor estimating that British purchasers of properties had almost €2 billion of loans outstanding to Cypriot banks at the time.
Costas Melas, head of the Borrowers Association (Syprodat) confirmed this, saying the number of burned borrowers was “definitely in the thousands”.
Their association has received many such complaints over the years.
“Banks were telling customers to take out loans in foreign currency – mostly Swiss francs but also in Japanese yen.
“Essentially it amounted to a scam, in my opinion.”
In many cases, contracts with banks were signed on behalf of the borrowers by lawyers given power-of-attorney.
To Melas’ knowledge, most cases in Cyprus have been resolved – either through amicable settlements or in the courts. He believes very few cases are still outstanding.
The last such case of Swiss francs the association has dealt with dates back three to four years, he recalled.
Melas urged people facing an auction on their property to immediately get an attorney to file for a court injunction.
Back to John, who remembers that banks were handing out Swiss franc loans “like confetti” at the time.
He knows of one case where a borrower won their court case against Alpha Bank, which agreed to re- convert the loan back to euros.
John also told us that his wife has Type 2 diabetes and suffers from severe visual impairment, being partially blind – making it even harder to move out.
The couple have grown attached to their home and feel that if the lender demonstrates some flexibility and patience, the matter can be resolved to the satisfaction of both parties.
Click here to change your cookie preferences